Turtle System 2
Turtle S2 channel breakout, 2N stop, 20-day exit.
USDJPY · D1 · Original trading hours
Source + EX5 + selected preset + checksums. Strategy Tester research build.
Turtle System 2
USDJPY D1 intrabar channel-breakout variant with Wilder-N stop and channel exit.
Selected public preset
ResearchMode 1; Variant 1; MagicNumber 26092142; RiskPercent 0.25; MaximumSpreadPips 2; RoundTripCommissionPerLot 7 (a sizing estimate, not a charged test fee); CampaignSession 0; CampaignSessionPolicy 1.
Rule and risk mechanics
Variant 1 enters one tick above the previous 40 completed daily-bar high or below its low. It uses 20-period Wilder N from completed D1 true ranges, a 2N stop and no fixed target. A held long exits when bid is at or below the previous 20-day low; a held short exits when ask is at or above the previous 20-day high. Source controls include 0.25% equity risk, a 1.5% daily brake and 2-pip spread gate.
Relationship to the strategy library
Related only by channel-breakout family: Donchian 20/10 Breakout is D1 close-based 20/10 with a 60-bar holding contract; Turtle uses intrabar 40-day entry, 2N and 20-day exit. See the legacy EA map for mapping scope.
Follow-up: ordinary long-channel exit observed
The unchanged selected public EA bought 0.01 lots of USDJPY.TFQ1 at 148.812 on 5 February 2024 at 02:37:09 broker time. On 7 March at 10:02:38 it sold at bid 147.930, the previous 20-completed-day low. This was an ordinary strategy close, not a tester-end close. The 2N stop at 146.077 was lower. A later 19 March entry was closed by the tester on 29 March and is counted separately.
The fixed extension ran from 1 February inclusive to 1 April exclusive on D1, with broker UTC+2 and UTC+3 after the US daylight-saving transition. It processed 5,869,589 real bid/ask ticks: 2 entries, 1 ordinary long-channel exit and 1 tester-forced close. Price P/L was −$3.20; recorded swap +$2.34; final balance $9,999.14 from $10,000. Added commission and delay were zero; financing history is unverified. This is functional path evidence, not a performance qualification.
The source initializes Wilder N from 201 completed daily bars. Its historical input includes excluded broker dates 22, 25–27 and 29 December 2023 and 1–2 January 2024. Those warmup limitations are retained; the February–March decision interval has no release exclusions. The short-channel exit, stop execution, risk sizing and restart behavior remain unproved by this case.
Earlier February 2024 observation
The receipt recorded 1 entry and a tester-forced close. It demonstrates lifecycle only; an ordinary channel exit was not observed. The approved new diagnostic window is 2024-02-01 inclusive to 2024-03-01 exclusive, on USDJPY.TFQ1 D1, with Model 4, a USD 10,000 deposit and 1:100 leverage at broker UTC+2. It added no commission or delay; recorded native swap history is unverified. It is separate from older archived broker charts and reports. It is not a profitability, restart, or full-rule-coverage result.
Package documentation and download; exact selected preset and binary identity: selected preset SHA-256 83ce0113322d5f231fb1c493ef30a372ae5c37181ff4bcf512878f89b9c30c9b; package binary SHA-256 1712b1d150af415b73a001e257dcf0528ebd4d2634a05dd946f3b2f6d4e26af7. Public functionality status: JSON evidence.
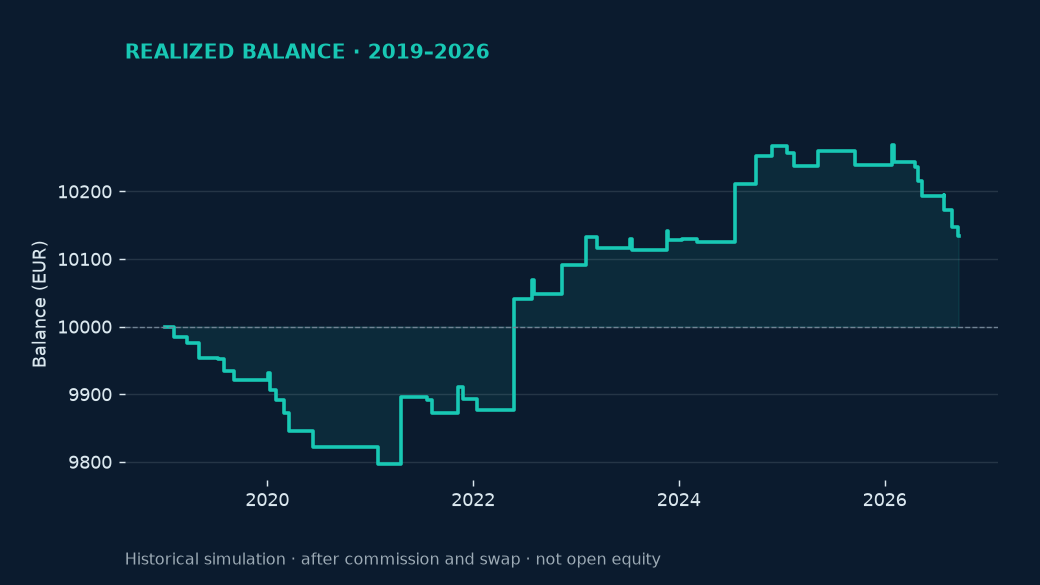
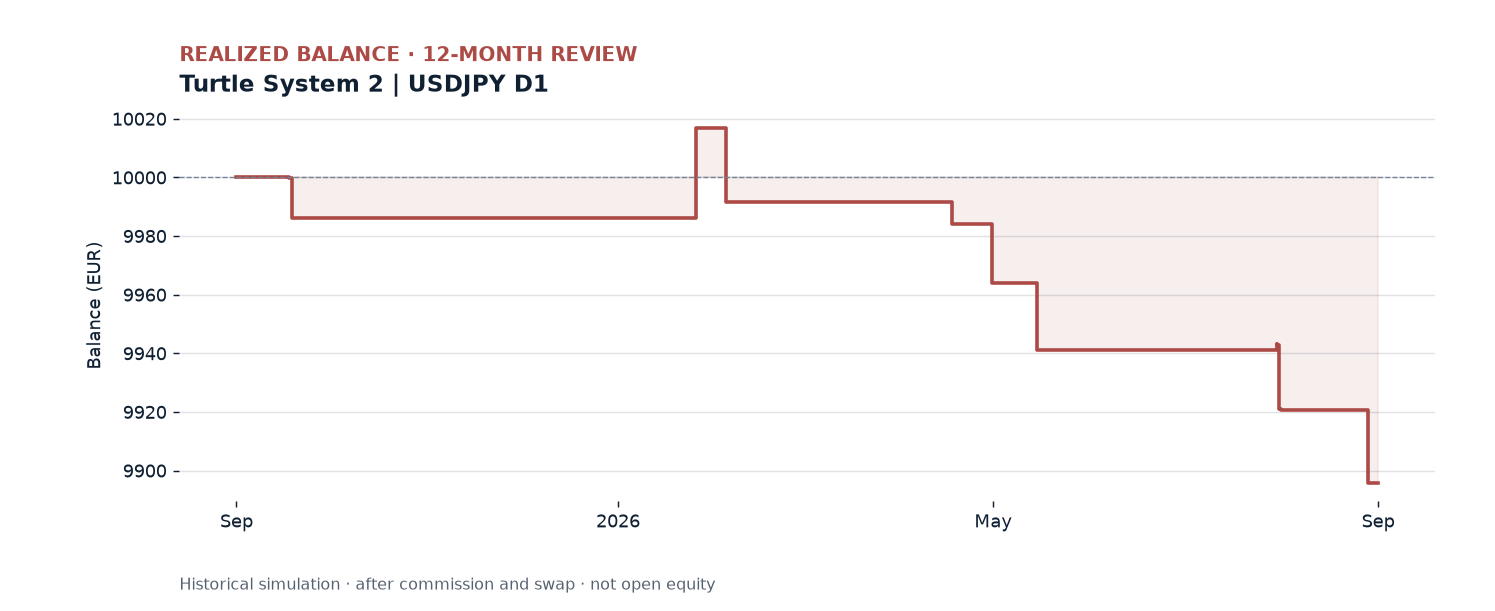
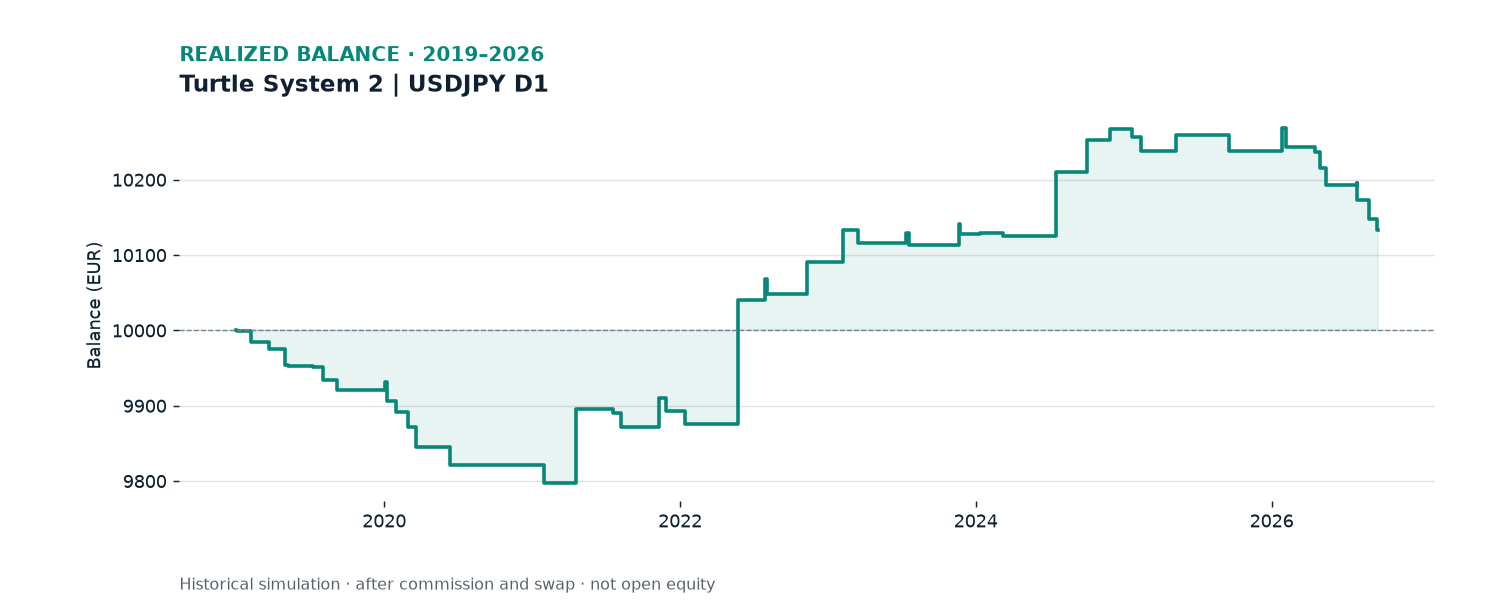
Selected configuration: rolling-year net EUR -104.32; full-period net EUR +133.86. Negative confirmation is retained in the archive.
How this strategy works
- Variant 1 enters intrabar when bid crosses at least one symbol tick beyond the preceding 40 closed D1-bar channel. Variants 0/2 use 55/80 bars.
- N is calculated as a 20-period Wilder-smoothed true range and the initial protective stop is 2N.
- No pyramiding is used. Exit a long when bid reaches the opposite 20-day channel low, or a short when ask reaches its high; there is no time exit.
The selected configuration uses USDJPY / D1, variant v1-s0. All indicator and session values used by this build are listed in the preset editor.
Original Turtle trading rules. The download is a documented research adaptation; results from the reference do not establish results for this EA.
Measured backtests
| Period / model | Net EUR | PF | Trades | Equity DD | Native report |
|---|---|---|---|---|---|
| Development 2019.01.01 → 2024.01.01 M1 OHLC screening | +123.80 | 1.34 | 31 | 3.18% | MT5 report |
| Validation 2024.01.01 → 2025.01.01 M1 OHLC screening | +138.79 | 34.77 | 5 | 0.95% | MT5 report |
| 12-month review 2025.09.01 → 2026.09.01 Real-tick mode + fallback | -104.32 | 0.24 | 9 | 1.46% | MT5 report |
| Long review 2019.01.01 → 2026.09.21 Real-tick mode + fallback | +133.86 | 1.25 | 48 | 2.89% | MT5 report |
Adjust the strategy preset
MT5 also validates parameter combinations and may reject incompatible inputs. Session modes use local London, New York and Tokyo hours. Broker-time conversion uses the configured winter UTC offset and DST rule. A session filter limits eligible entries; it does not change the underlying strategy signal or create trades where none qualify. Policy 2 also closes before the chosen session ends.
Install and reproduce the archived broker test
- Download and extract the ZIP. Copy
TFPublishedResearch.ex5intoMQL5/Experts/TradeForexin the MT5 data folder. Keep MQ5 and all MQH headers together if compiling. - Open Strategy Tester, select the EA, USDJPY and D1. The build rejects normal chart execution.
- Load the included
selected-test.setor a preset downloaded above. Symbol, chart timeframe, dates, deposit and tick model are tester settings outside the .set file. - For confirmation choose “Every tick based on real ticks”, EUR 10,000, 1:30 leverage and 100 ms delay. Use 2025.09.01–2026.09.01 or 2019.01.01–2026.09.21; retain the generated report and Journal.
- Allow MT5 to obtain the available broker history. Compare actual date coverage, costs, trade count and history quality; a later download or different broker server can change the result.
Read the general MT5 installation guide; this package’s tester-only restriction takes precedence over normal chart-activation steps.
Limits of the archived broker results
- Daily channels depend on broker daily boundaries.
- No pyramiding is an explicit adaptation.
- These are retrospectively selected historical tests. Development, validation and review periods overlap previously inspected history; this is not a fresh independent holdout.
- The balance plots show realized outcomes. Equity drawdown includes floating positions and must not be inferred from the balance line alone.
- Available native ticks and fallback are accepted. Missing ticks, historical spread paths and cost assumptions limit confidence; profitable history does not guarantee future profitability.
- RiskPercent is an entry-sizing estimate, not a hard loss cap. Costs, gaps and slippage can exceed that estimate; some legacy sizing excludes transaction costs.
Additional cost stress adds 25% of the absolute commission and swap amounts: 12-month stressed net EUR -110.27; long-period stressed net EUR +70.69. This is not a full spread or slippage stress.
Files and reproducibility
Each ZIP includes MQ5 source, required headers, EX5, README, selected-test.set, selection.json and SHA256SUMS.txt. Compiled builds and measured results are unchanged by this documentation update.
ZIP SHA-256abf5c8acfc3dd90fa10cf533eb33ddd6f5285292878ada192235dfc28c92fe1c
Tested EX5 SHA-2561712b1d150af415b73a001e257dcf0528ebd4d2634a05dd946f3b2f6d4e26af7
Selection criteria and all strategy categories · Frozen selection record